Virginia’s storm record
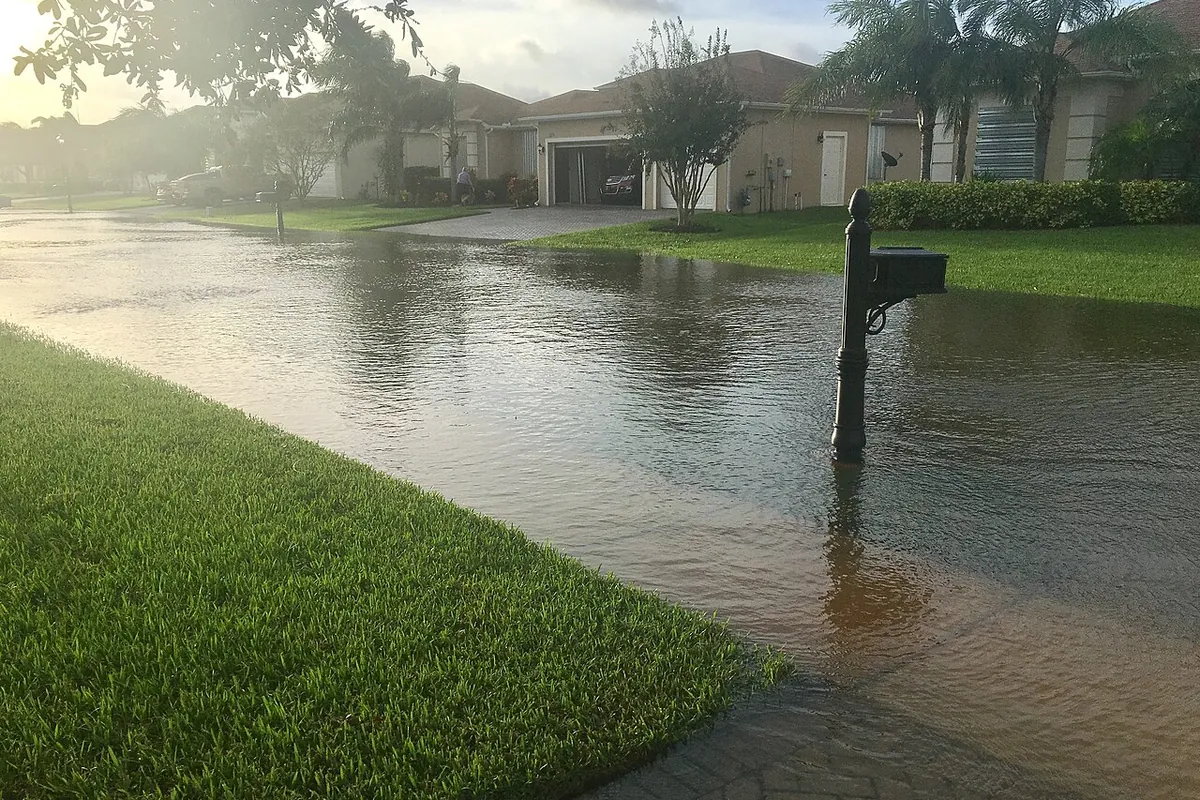
Hurricane Isabel in September 2003 remains the benchmark for modern Virginia storms. It brought record surge to parts of the Chesapeake Bay, flooded Old Town Alexandria and downtown Norfolk, and pulled down trees and power lines as far inland as Richmond. Hurricane Irene in 2011, Sandy’s outer bands in 2012 and Matthew’s flooding rains in 2016 followed. Nor’easters add a second season. The Ash Wednesday Storm of 1962 reshaped Virginia Beach’s oceanfront, and winter coastal storms still drive water into Sandbridge, Ocean View and the Eastern Shore.
Wind, water and the line between them
Homeowners and commercial policies usually exclude flood and storm surge, which belong under a separate flood policy such as one written through the National Flood Insurance Program. A hurricane claim appraisal therefore starts by separating the damage:
- Roof, siding, window and soffit damage caused by wind.
- Interior water from wind-driven rain through an opening the storm created.
- Rising water and surge damage that belongs on the flood claim.
- Tree impacts, which may fall under different policy provisions.
When one storm causes both wind and flood damage, the estimates have to fit together without double counting. We document the high-water line, interior moisture patterns and roof openings so each policy pays its share.
Named-storm and hurricane deductibles
Many coastal Virginia policies carry a percentage deductible that applies only to hurricane or named-storm losses. On a $450,000 dwelling limit, a 2% deductible is $9,000. Whether it applies can depend on watches, warnings and timing, which is why we read the trigger wording first.
Coastal construction details
Hampton Roads homes often need corrosion-resistant fasteners, enhanced underlayment, impact-rated openings in some areas, and elevation work when substantial damage triggers local floodplain rules. Those requirements belong in the repair scope when your policy covers them.
Questions about hurricane & nor’easter appraisal
Can appraisal resolve a flood insurance claim?
Standard NFIP flood policies have their own appraisal provision for disputes about the amount of loss, with federal rules and deadlines. We can help value the loss, but follow your flood policy’s procedures carefully.
What if the insurer says all the interior water was flood?
Moisture mapping, staining patterns and roof or window openings help show which water came from above and which came from below.