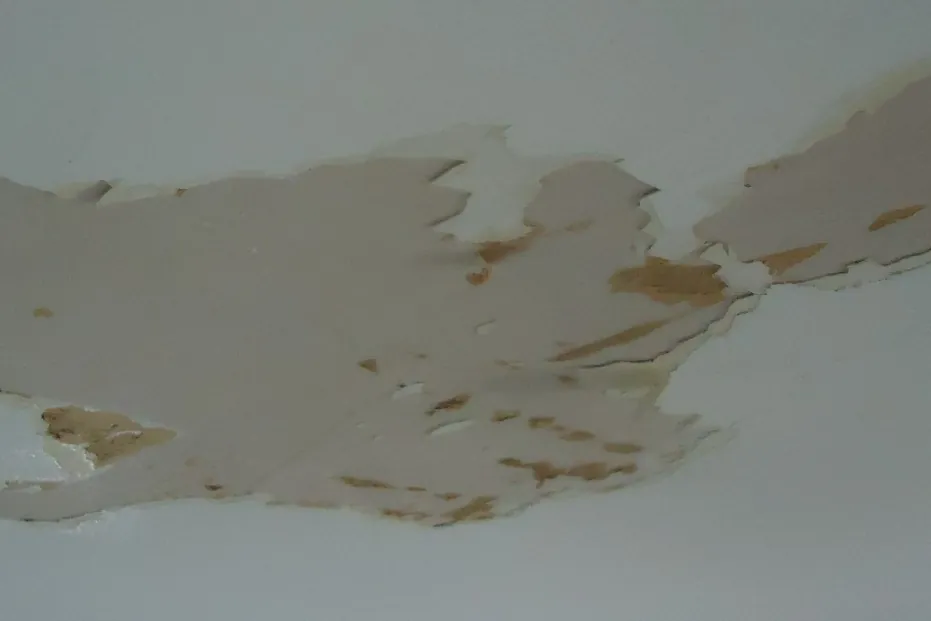
Where water damage claim appraisal disputes come from
Virginia winters are milder than New England’s, but cold snaps still freeze pipes in crawlspaces, exterior walls and seasonal homes in the mountains, especially in homes built for a mild climate. Add washing machine hoses, water heaters, ice-maker lines and roof leaks, and water losses are among the most common claims we see.
Disputes tend to center on:
- Mitigation invoices that the insurer cuts as excessive equipment or drying time.
- Scope of tear-out, such as how much drywall, insulation and flooring had to go.
- Matching: continuous flooring, cabinets and countertops that can’t be patched.
- Mold remediation, which policies often limit with a sub-limit.
- Cause and duration, because many policies exclude repeated seepage over 14 days or more.
How we value a water loss
We review moisture logs, drying records and photos from the mitigation company, then inspect the rebuild scope ourselves. Our estimate prices each phase: demolition, drying, cleaning, rebuild and contents handling. That way the panel can see the full cost of putting the home back, not just the cost of drying it.
Crawlspaces and basements
Much of Hampton Roads and Southside builds on crawlspaces, while Northern Virginia and the mountains favor basements. Each hides damage differently. Wet subfloor, joists and insulation under a house are easy to leave out of an estimate.
Questions about water damage claim appraisal
The insurer says the leak was long-term. What now?
Long-term seepage exclusions are common. Plumbing reports, moisture readings and the condition of the materials can help show when the water actually escaped.
Is mold covered?
Often only up to a sub-limit, and only when it results from a covered water loss. Check your policy’s fungi or mold endorsement.